Nvidia reported a major earnings beat on Wednesday night for the past quarter (Q2): Revenue soared to 96.2 billion, with company growing 106% YoY. The earnings per share was $2.22 (beating 2.10 expected) and the data center revenue was $89B compared to $85.4B that was expected. The adjusted gross margins for this quarter were in line with expectations: 75%.
Jensen Huang, founder and CEO, cast an upbeat note in the press release: "AI is at an inflection point," with the past quarter's revenue alone generating more than 53 billion dollars (up from 24.7 billion the equivalent period last year. The company said it was guiding revenue to be at 108 billion for Q3, beating the expected consensus $104.2B but missing the most bullish forecast of some investors, which had eyed a $108 billion revenue for the quarter. Its adjusted gross margin for Q3 are guided at 74%, slightly below the 75% investors said.
Immediate reaction was moderate, with stock dropping some 1.5% in the immediate aftermath.
The report arrives with the AI chip giant's stock facing an unusual dynamic: Even when Nvidia beats expectations, investors have increasingly punished the stock rather than rewarded it.
Why guidance beat expectations but investors stayed wary
Nvidia's third-quarter revenue outlook also came in above what analysts had modeled, yet that upbeat forecast didn't fully erase investor unease. Four specific concerns kept a lid on enthusiasm even as the numbers themselves impressed.
The most notable is China. Nvidia's third-quarter guidance assumes it will book zero data-center compute revenue from Chinese customers, a stark reminder that export restrictions and broader trade friction with Beijing remain an open wound rather than a resolved issue.
Competitive pressure is also building on two fronts. Rivals are pushing harder into inference chips, the workhorse silicon used to run already-trained AI models rather than build them, narrowing one of Nvidia's advantages. At the same time, some of its biggest customers – including Microsoft, Alphabet, and Amazon – continue investing in their own custom AI chips, a long-term threat to Nvidia's grip on the cloud-computing giants that currently account for a huge share of its sales.
Costs are the third worry. A global shortage of memory chips has pushed up component prices, squeezing margins just as Nvidia has signaled plans to raise prices on some AI systems – a move that could help offset costs but risks friction with customers already facing tighter AI budgets.
Finally, there's the market's own well-worn pattern: Nvidia's stock has repeatedly struggled to hold gains or has pulled back outright in the sessions right after strong earnings, simply because expectations heading into each report are already so elevated that even a clean beat can disappoint relative to what's priced in.
Nvidia tops estimates again – but can it finally break its post-earnings losing streak?
Nvidia posted another quarter of blowout results on Wednesday evening, topping Wall Street's targets on both profit and sales as the AI chip leader's growth engine kept running hot. According to consensus figures tracked by LSEG, the company earned $2.22 per share on an adjusted basis, ahead of the $2.10 analysts had projected, while revenue came in at $96.22 billion versus expectations of $92.17 billion.
That's a beat of roughly 5.7% on the bottom line and about 4.4% on the top line – continuing a run in which Nvidia has now cleared Wall Street's bar in nine of its last ten reported quarters.
Growth still accelerating nearly four years into the AI boom
The scale of Nvidia's expansion remains striking given how long the current AI cycle has run. Revenue for the quarter came in more than double what the company generated in the same period a year earlier, when sales stood at $46.7 billion – a pace of growth few large companies sustain even one year into a boom, let alone nearly four years after OpenAI's ChatGPT first ignited the current wave of AI investment.
Nvidia's position at the center of that boom has also evolved. Beyond selling the chips that power the world's most advanced AI models, the company has increasingly become a financier of the AI buildout itself, offering backstops and other funding arrangements that help get new data centers built and online.
Investors have grown more cautious even as results stay strong
Even with the business firing on all cylinders, Wall Street's enthusiasm has noticeably cooled this year. Heading into Wednesday's report, Nvidia shares were up only about 13% for the year – a modest gain that only slightly outran the Nasdaq, especially set against the stock's historic three-year run. Two pressures loom over the outlook: rising competition from rivals including AMD and Google, and a worsening global memory-chip shortage that is pushing up Nvidia's input costs with no clear end in sight.
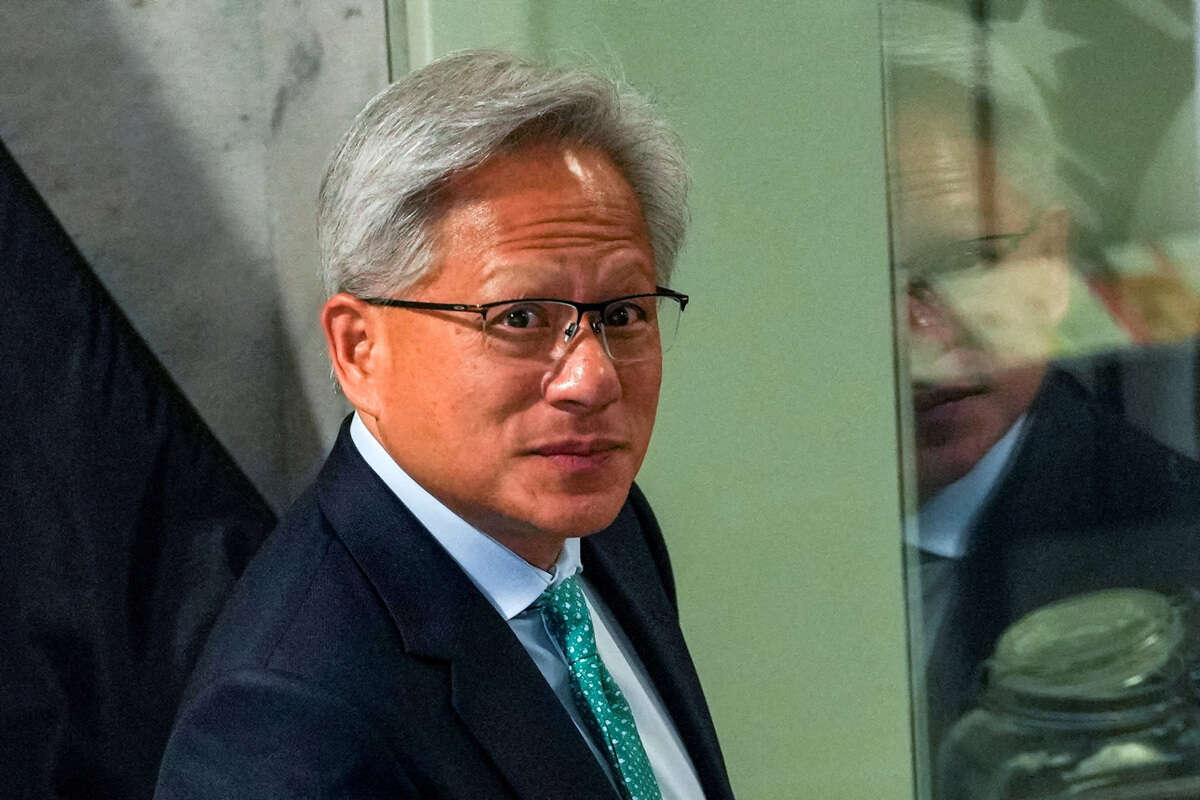
NVIDIA CEO Jensen Huang speaks during the Live Keynote Pregame during the Nvidia GTC conference (left: Google CEO Sundar Pichai) / Jim WATSON / AFP; AP Photo/Jeff Chiu, File; Yossi Hai Hanuka;

NVIDIA's CEO Jensen Huang against the backdrop of an Israeli NVIDIA office (Courtesy of NVIDIA Israel; Patrick T. Fallon / AFP)
The pattern this report needs to break
Wednesday's beat arrives against a backdrop that has become one of the more curious stories on Wall Street: Nvidia has beaten estimates in four straight prior quarters, and the stock fell after every one of them. That losing streak, detailed in the table below using data through the May 2026 report, shows how disconnected the size of a beat has become from the market's reaction:
-
Q1 FY2027 (May 2026): Beat by about 6%, stock fell 1.8% the next session.
-
Q4 FY2026 (Feb. 2026): Beat by about 5%, stock fell 5.5%.
-
Q3 FY2026 (Nov. 2025): Beat by about 3%, stock fell 3.2%.
-
Q2 FY2026 (Aug. 2025): Beat by about 4%, stock fell 0.8%.
-
Q1 FY2026 (May 2025): Beat by about 8%, stock rose 3.3%.
Looking back further, across 42 earnings reactions since 2016, Nvidia has closed higher the next session 24 times and lower 18 times – a 57% win rate – with an average absolute move near 6.7% in either direction, according to data compiled by SimianX. That track record suggests volatility, not direction, is the safer bet.
Ahead of this report, options markets had priced in an expected next-day swing of roughly plus-or-minus 5.4%, implying as much as $280 billion of movement in Nvidia's market value once trading resumes, according to Reuters.
Why a beat alone may not settle the debate
As Nvidia's beats have become the expectation rather than the exception, the market's attention has shifted toward what comes next rather than what already happened. Investors are weighing forward guidance, the durability of data-center demand, gross-margin trends, and whether rising memory costs and stiffer competition from AMD and Google start to bite into future quarters. Against that backdrop, even a headline beat like Wednesday's $2.22-per-share result and $96.22 billion in revenue – paired with above-consensus guidance – may not be enough on its own to end the stock's four-quarter slide the day after earnings. The China revenue exclusion, the custom-silicon threat from major cloud customers, and mounting memory costs all give investors reason to treat this report with more caution than the raw numbers alone would suggest.